

Balancing everyday living expenses with existing debt obligations can feel like a constant uphill struggle. When food, housing, and utility costs rise, finding extra money to throw at credit cards or personal loans becomes increasingly difficult.
However, debt repayment and managing daily living costs do not have to be mutually exclusive. By adopting modern, realistic budgeting methods, you can cover your essential living expenses while steadily eliminating what you owe.
Quick Summary: Managing living costs while paying off debt requires a two-front financial strategy. First, categorize expenses using a structured system like the 50/30/20 or Zero-Based budget to secure essential needs. Second, channel all surplus funds toward debt using either the Debt Avalanche method (prioritizing high-interest rates) or the Debt Snowball method (prioritizing lowest balances for psychological momentum).
1. Audit Your Current Cash Flow
Before creating a realistic budget, you must gain total visibility over where your money actually goes each month. A common pitfall in household budgeting is relying on estimates rather than hard transaction history.
Track 60 to 90 Days of Spending
Review bank statements, credit card bills, and receipt logs from the past three months. Group your expenses into two primary categories:
-
Fixed Essential Expenses: Non-negotiable bills that remain relatively stable, such as rent or mortgage payments, insurance premiums, debt minimum payments, and basic utilities.
-
Variable and Discretionary Expenses: Costs that fluctuate weekly or monthly, including groceries, dining out, subscriptions, fuel, entertainment, and personal care.
2. Choose a Purpose-Built Budgeting Framework
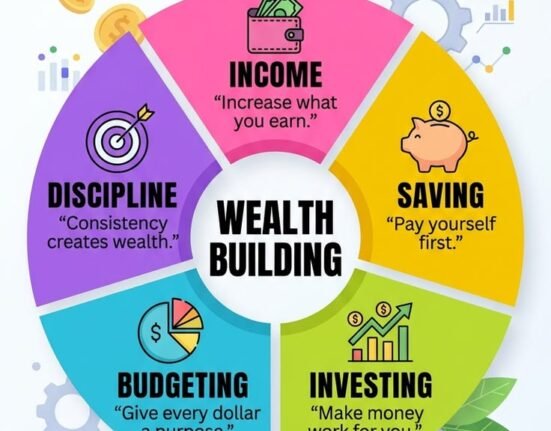
A budget should never feel like a financial straightjacket. Instead, view it as a tool that gives every dollar a specific job. Two budgeting frameworks work exceptionally well when managing high living costs alongside debt payoff.
The 50/30/20 Rule (Modified for Debt Focus)
The classic 50/30/20 rule allocates 50% of net income to needs, 30% to wants, and 20% to savings and debt payoff. When living costs are elevated or debt balances are high, adjust the ratio:
-
50% to 60% Needs: Essential housing, utilities, groceries, and transportation.
-
10% to 15% Wants: Minor discretionary spending to prevent budget burnout.
-
25% to 30% Debt Payoff and Savings: Minimum debt payments plus extra principal payments and emergency funds.
Zero-Based Budgeting
With zero-based budgeting, your income minus your expenses equals zero at the end of the month. Every dollar received is assigned to a specific category (e.g., $1,200 rent, $400 groceries, $300 debt payoff, $100 buffer). This eliminates unallocated cash that often disappears into micro-purchases.
Incorporating modern personal finance tips into your monthly routine helps maintain consistency across whichever budgeting model you select.
3. Reduce Essential Living Costs Without Sacrificing Stability
Lowering core living expenses creates immediate breathing room in your budget, allowing you to redirect cash directly toward debt principal.
Optimize Food and Grocery Expenses
Groceries are often the largest variable cost in a household budget. Small, strategic shifts yield substantial monthly savings:
-
Meal Plan Around Sales: Plan weekly meals using store circular discounts rather than buying ingredients on impulse.
-
Reduce Food Waste: Store produce properly and utilize freezer-friendly recipes to stretch grocery value.
-
Audit Subscription Services: Cancel recurring app memberships, meal delivery kits, and streaming channels you rarely use.
Negotiate Fixed Bills
Many service providers offer unadvertised retention rates or hardship programs. Call your internet provider, mobile carrier, and insurance agents annually to request lower rates or shop for competing quotes.
Executing practical financial planning strategies ensures that any recurring savings secured from providers go directly toward paying down balance accounts rather than disappearing into daily spending.
4. Select an Effective Debt Payoff Strategy
Once your living costs are controlled and you have generated a monthly surplus, apply a proven debt payoff accelerator method. Continue paying the minimum balance on all debts, but channel all extra funds into one target account.
| Payoff Method | Core Strategy | Ideal For |
| Debt Avalanche | Target the debt with the highest interest rate first. | Individuals motivated by mathematical efficiency and saving maximum money on interest. |
| Debt Snowball | Target the debt with the smallest total balance first. | Individuals who need quick psychological wins to stay motivated over time. |
5. Build a Micro Emergency Fund First
One of the main reasons people fall back into debt while trying to pay it off is unexpected expenses, such as car repairs or medical bills.
Before funneling every spare dollar toward debt payoff, save a micro emergency fund of $500 to $1,500. This buffer absorbs minor life surprises without requiring you to rely on high-interest credit cards again.
Leveraging specialized budgeting tools like spreadsheet templates or tracking apps makes monitoring both your emergency cash buffer and debt reduction progress seamless.
For more in-depth technology guides, actionable digital strategies, and real-time industry updates, explore our full library at newsupto.com.
Leave feedback about this