

An emergency fund serves as your financial shock absorber—a dedicated cash reserve built to cover unexpected medical bills, car repairs, or sudden job disruptions without forcing you into high-interest debt.
However, leaving three to six months of living expenses sitting in a traditional bank account earning near-zero interest allows inflation to erode your purchasing power over time.
To protect their reserves, cash-conscious savers generally turn to two options: High-Yield Savings Accounts (HYSAs) or Short-Term Treasury Bills (T-Bills).
While both options provide exceptional safety, they operate differently when it comes to state taxes, rate guarantees, and instant liquidity.
Here is a side-by-side breakdown of High-Yield Savings Accounts versus short-term Treasury bills to help you decide where to park your emergency fund.
HYSA vs. Short-Term Treasury Bills Summary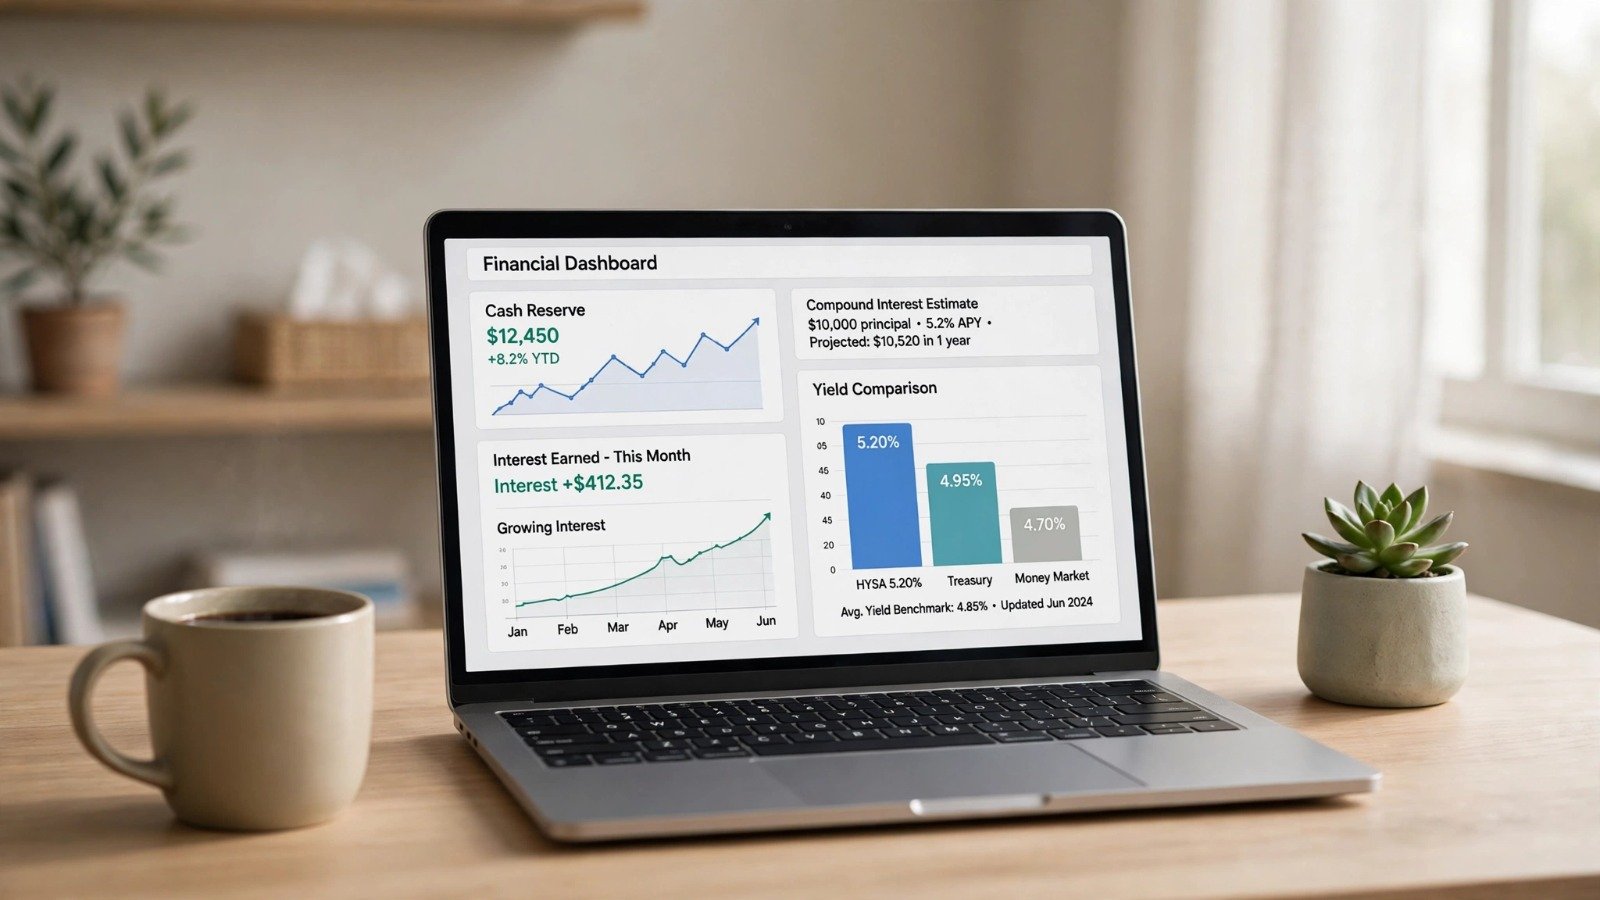
Which option works best for your emergency cash depends on where you live and how quickly you might need access to your funds:
-
Choose a High-Yield Savings Account if: You want instant, hassle-free access to your cash via online transfers, live in a state with zero income tax, or prefer zero management effort.
-
Choose Short-Term Treasury Bills if: You live in a high-tax state (like California, New York, or New Jersey), hold an emergency balance above FDIC limits ($250,000), or want to lock in a fixed yield for up to 12 months.
-
The Hybrid Solution (Best for Most): Keep 1 to 2 months of expenses in a HYSA for instant access, and place the remaining 3 to 4 months in a rolling T-bill ladder.
Understanding the Fundamentals
Before comparing features, it helps to review how each financial product operates.
High-Yield Savings Account (HYSA)
A HYSA is an open-ended deposit account offered by online banks or credit unions. It functions like a standard savings account, but pays interest rates significantly higher than the national traditional bank average.
Your deposit is insured up to $250,000 per depositor, per institution, by the Federal Deposit Insurance Corporation (FDIC) or National Credit Union Administration (NCUA). The interest rate on a HYSA is variable, meaning the bank can raise or lower it at any time based on overall market conditions.
Short-Term Treasury Bills (T-Bills)
Short-term Treasury bills are short-term debt obligations issued by the U.S. government with terms ranging from 4 weeks to 52 weeks (1 year).
Instead of paying regular monthly interest payments, T-bills are sold at a discount from their face value. When the bill matures, the U.S. government pays you the full face value. The difference between the discounted purchase price and the final payout is the interest you earn.
Because they are backed directly by the full faith and credit of the U.S. government, T-bills carry virtually zero default risk and have no dollar limit on government backing.
Direct Comparison: HYSA vs. Short-Term T-Bills
| Feature / Metric | High-Yield Savings Account (HYSA) | Short-Term Treasury Bills (T-Bills) |
| Current Yield Behavior | Variable (Can change daily or monthly). | Fixed once purchased (Locked for the term). |
| Safety / Guarantee | FDIC/NCUA insured up to $250,000 per bank. | Backed by full faith of U.S. Government (No limit). |
| State & Local Income Tax | Fully taxable at Federal, State, and Local levels. | 100% Exempt from State & Local income tax. |
| Federal Income Tax | Fully taxable. | Fully taxable. |
| Liquidity / Withdrawal | Immediate or 1–2 day bank transfer. | Locked until maturity (or sold on secondary market). |
| Setup & Friction | Low (Open account in minutes online). | Moderate (TreasuryDirect or brokerage account). |
Key Decision Factors for Your Emergency Cash
1. The State Tax Advantage (Where T-Bills Often Win)
One of the most significant differences between these options is tax treatment.
Interest earned from a HYSA is subject to federal, state, and local income taxes. However, interest earned from U.S. Treasury bills is completely exempt from state and local income taxes.
-
If you live in a state with no income tax (such as Florida, Texas, or Washington), the tax exemption provides no extra benefit. In this case, simply choose the option with the higher headline interest rate and lowest setup friction.
-
If you live in a high-tax state (such as California, New York, or Minnesota), a T-bill paying 4.25% will often yield a higher net after-tax return than a HYSA paying 4.35% once state tax deductions are factored in.
2. Liquidity and Emergency Access
An emergency fund must be available when an urgent need arises.
-
HYSA Liquidity: Unmatched convenience. You can transfer money from an online savings account to your primary checking account in a day or two without penalties.
-
T-Bill Liquidity: T-bills require holding the security until its maturity date (e.g., 4, 13, or 26 weeks) to collect the full yield. If you need cash early, you must sell the bill on the secondary market through a brokerage account, which introduces minor hassle and slight price fluctuation risk if interest rates have shifted.
3. Rate Stability: Variable vs. Fixed Yields
-
When central bank interest rates fluctuate, HYSA interest rates adjust automatically. If benchmark interest rates drop over the coming months, your bank will lower your savings account APY.
-
T-bills lock in your exact yield at the moment of purchase for the entire term. If you buy a 26-week T-bill, your yield will not change regardless of overall market shifts over those 6 months.
Learn how to structure your overall personal spending before allocating savings by reading our beginner guide to budgeting.
Discover step-by-step methods to calculate your ideal 3-to-6-month cash cushion in our guide on how to build an emergency fund.
If your cash flow changes from month to month, explore our strategy breakdown on debt payoff strategies for variable income.
How to Build a “T-Bill Ladder” for Continuous Liquidity
If you want the state tax benefits of Treasury bills without locking up all your emergency cash at once, set up a Treasury Bill Ladder.
By purchasing 4-week Treasury bills staggered one week apart, one bill matures every single week.
If you do not experience an emergency, you let the maturing bill automatically roll over into a new 4-week bill. If an emergency occurs, you simply let the next maturing bill payout straight into your bank account as cash.
Want More Insights to Grow Your Digital Presence & Daily Productivity?
Whether you need to fix your website’s technical performance or build a smarter, burnout-free work routine, NewsUp To delivers practical guides to keep you ahead.
Leave feedback about this