
Navigating the world of personal finance often involves dealing with credit terminology that sounds nearly identical. Two terms that frequently confuse borrowers are credit score and credit report. While both are critical tools that banks and lenders use to evaluate your financial reliability, they represent two distinct parts of your credit profile.
Understanding how your credit report feeds into your credit score helps you take control of your financial health, qualify for better loan interest rates, and catch errors before they harm your borrowing power.
Below is a complete, easy-to-understand breakdown of the credit score vs credit report difference and how both affect your financial life.
1. What Is a Credit Report?
A credit report is a detailed statement of your personal financial history related to borrowed money. Major credit bureaus (such as Equifax, Experian, and TransUnion) compile this data from your banks, credit card issuers, and lenders.
Your credit report contains four primary categories of information:
-
Personal Identification: Your full name, current and past addresses, Social Security number, and employment history.
-
Credit Accounts (Tradelines): A full list of credit accounts, including credit cards, mortgages, auto loans, and student loans. It includes account open dates, credit limits or original loan amounts, current balances, and payment status.
-
Public Records: Bankruptcy filings, legal judgments, or tax liens associated with your name.
-
Credit Inquiries: A record of who has accessed your credit history over the past two years, categorized into hard inquiries (lender loan applications) and soft inquiries (background checks or pre-approved offers).
2. What Is a Credit Score?
A credit score is a three-digit mathematical snapshot that summarizes the risk level of lending you money. Statistical models (such as FICO or VantageScore) analyze the data in your credit report to calculate this number, which typically ranges from 300 to 850.
The higher your score, the lower the risk you represent to lenders. FICO credit scores are broadly categorized as follows:
-
Exceptional (800 – 850): Qualifies for the lowest interest rates and best credit terms available.
-
Very Good (740 – 799): Demonstrates strong financial reliability to almost all lenders.
-
Good (670 – 739): Near or slightly above the average consumer score; easily approved for standard loans.
-
Fair (580 – 669): Below average; may face higher interest rates or require collateral.
-
Poor (300 – 579): Indicates significant risk; loan applications may be denied or require a co-signer.
3. Credit Score vs Credit Report Difference Table
| Feature | Credit Report | Credit Score |
| Format | Detailed multi-page document | Single 3-digit number (300 to 850) |
| Contents | Full payment history, balances, accounts, inquiries | A statistical score calculated from the report data |
| Source | Compiled by credit bureaus (Equifax, Experian, TransUnion) | Generated by scoring models (FICO, VantageScore) |
| Primary Purpose | Shows lenders specific details on how you manage debt | Gives lenders a fast snapshot of your overall credit risk |
| How to Fix | Dispute incorrect account details or reported late payments | Improve habits like paying on time and lowering credit card balances |
4. How Lenders Use Both Tools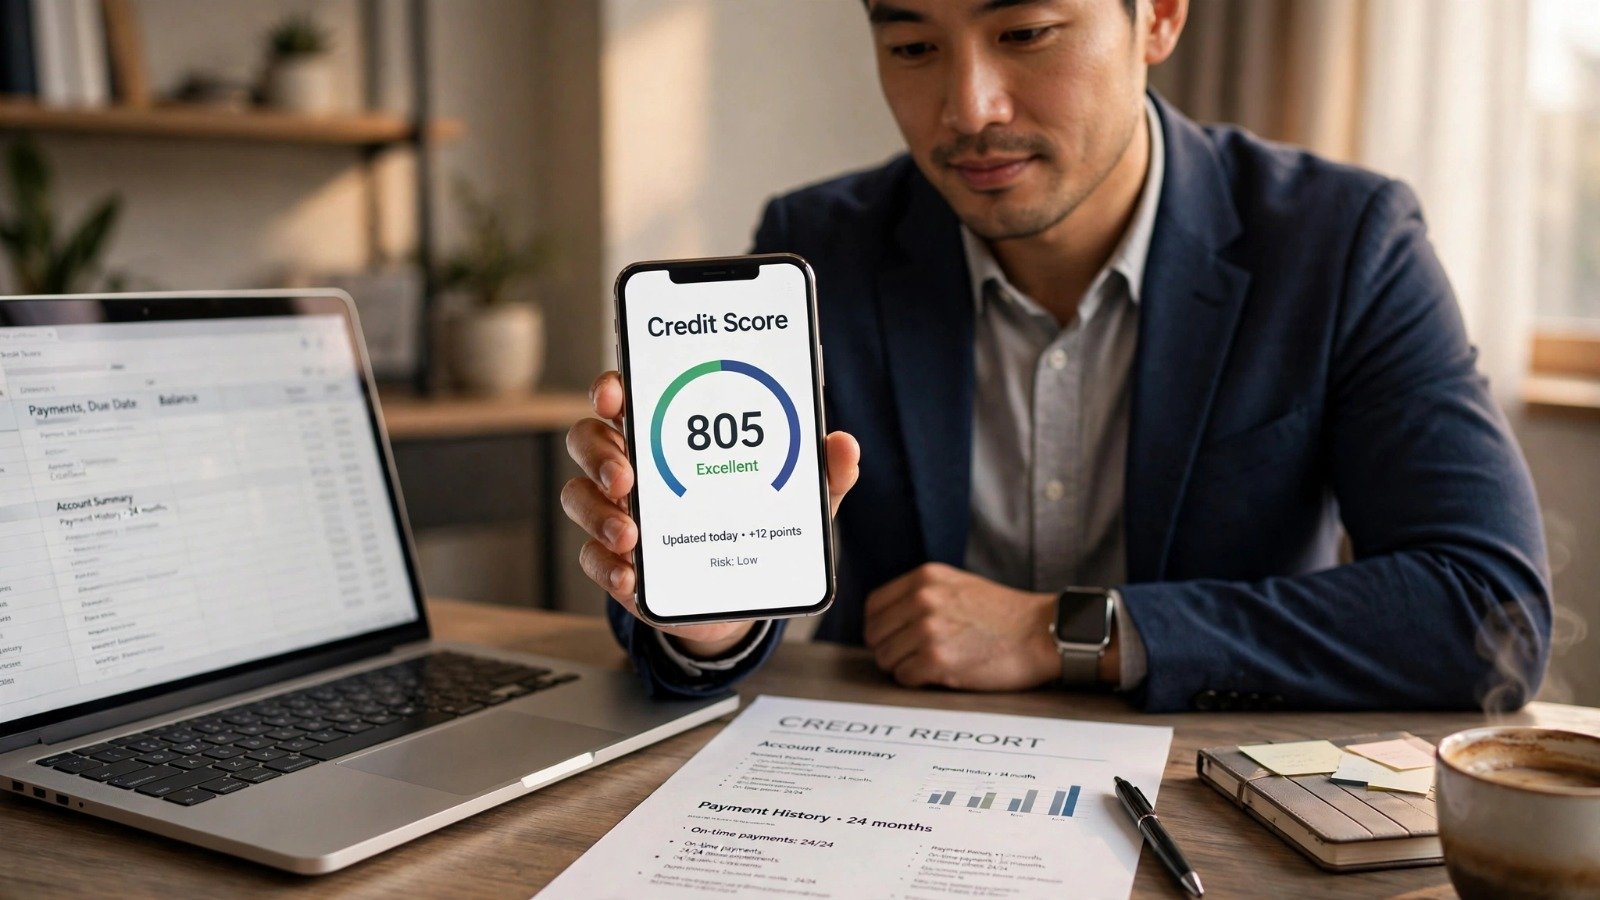
Lenders evaluate both your score and report during different stages of the application process:
-
The Initial Screening (Credit Score): When you apply for a credit card or auto loan, automated lender systems check your credit score first. If your score meets their minimum threshold, your application moves to approval or manual underwriting.
-
The Deep Review (Credit Report): For major financial commitments like home mortgages, underwriters look beyond the number and examine your actual credit report. They inspect your debt-to-income ratio, check for recent late payments, and verify that you do not have active collection accounts.
Before applying for major loans, establishing personal cash buffers covered in how to build an emergency fund ensures you can manage monthly debt repayments even during unexpected financial setbacks.
5. How to Check and Improve Your Credit Profile
Improving your credit score requires managing the underlying data inside your credit report.
-
Check Your Report for Errors: You can request free copies of your credit reports annually from the major bureaus via AnnualCreditReport.com. Review your accounts for incorrect balances, unauthorized accounts, or outdated negative marks.
-
Pay All Bills On Time: Payment history accounts for 35% of your total credit score calculation. Setting up automated calendar reminders prevents missed payment dates.
-
Keep Credit Card Balances Low: Credit utilization (the ratio of your credit card balances relative to your credit limits) accounts for 30% of your score. Aim to keep total credit utilization below 30%.
-
Avoid Opening Too Many Accounts at Once: Multiple hard inquiries within a short period can lower your score temporarily.
Integrating credit management into a clear spending framework outlined in how to make a budget for beginners keeps monthly debt obligations well within your income limits. Understanding how smart debt differs from consumer obligations in our good debt vs bad debt explanation helps you build long-term wealth responsibly.
Want More Insights to Grow Your Digital Presence & Daily Productivity?
Whether you need to fix your website’s technical performance or build a smarter, burnout-free work routine, NewsUp To delivers practical guides to keep you ahead.
Leave feedback about this