
When comparing savings accounts or checking rates at online banks, you will consistently see a percentage number labeled APY. While most people know that a higher percentage is better for their savings, many do not fully understand what APY stands for or how it differs from a standard interest rate.
Understanding how APY works is essential for evaluating high-yield savings accounts, certificates of deposit (CDs), and money market accounts, helping you earn maximum interest on your hard-earned money.
Below is a complete, easy-to-understand guide explaining what APY in a savings account is, how compounding works, and how to use it to grow your money faster.
1. What Does APY Mean?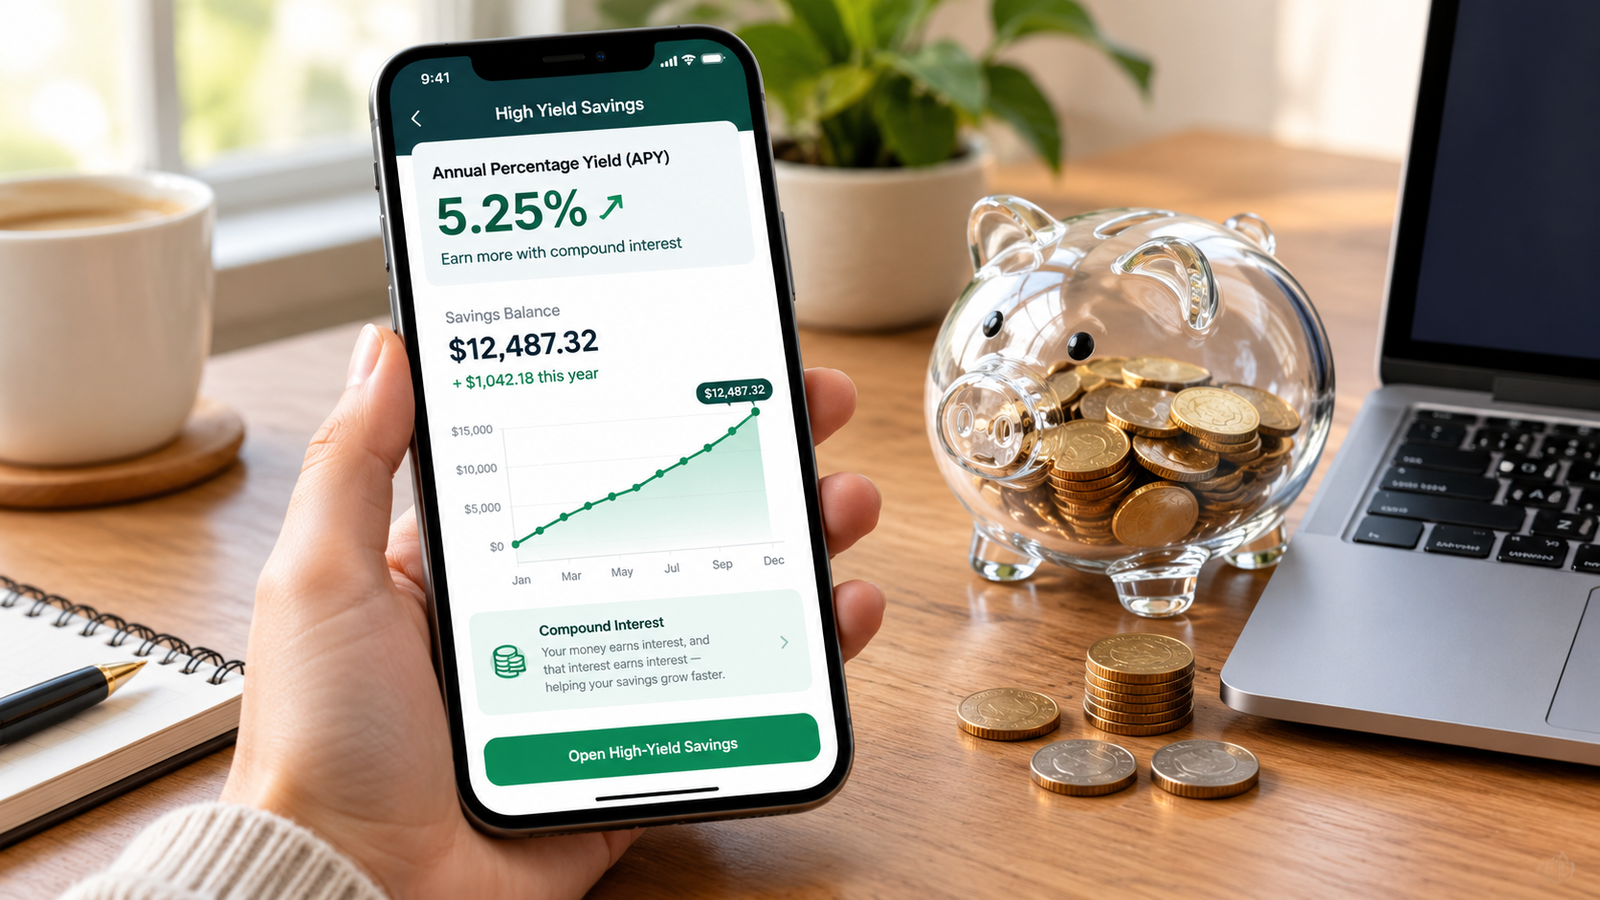
Annual Percentage Yield (APY) reflects the true annual return on your deposited funds. Unlike a simple interest rate, APY accounts for interest compounding over time.
-
Simple Interest: Interest calculated solely on your original deposit (the principal balance).
-
Compound Interest: Interest earned on your original deposit plus the accumulated interest from previous periods.
-
Why Banks Use APY: Federal regulations require banks to display APY so consumers can accurately compare earning potential across different financial institutions, regardless of how frequently each bank compounds interest.
2. How Compound Interest Drives APY
To see APY in action, consider how compounding frequency affects your total earnings. When a bank compounds interest daily or monthly, that earned interest is added to your account balance. In the next period, you earn interest on top of that new, higher balance.
Example Calculation
Imagine you deposit $10,000 into a savings account with a 5.00% base interest rate:
-
Simple Interest (No Compounding): You earn $500 over one year (5.00% total yield).
-
Monthly Compounding: Your account earns interest every month. By the end of the year, you have earned $511.62, making your effective APY 5.12%.
-
Daily Compounding: Your account earns micro-interest every day. By the end of the year, your return reaches $512.67, yielding an effective APY of 5.13%.
The mathematical formula for APY incorporates compounding frequency as follows:
Where $r$ represents the nominal interest rate and $n$ represents the number of compounding periods per year.
3. APY vs. APR Difference
A common point of confusion in banking is the difference between APY and APR (Annual Percentage Rate).
| Feature | APY (Annual Percentage Yield) | APR (Annual Percentage Rate) |
| Primary Use | Savings products (Savings, CDs, Money Market) | Borrowing products (Loans, Mortgages, Credit Cards) |
| Includes Compounding? | Yes | No (Simple interest calculation) |
| Impact on Consumer | Higher percentage means more money earned | Lower percentage means less interest paid |
| Focus | How fast your money grows | The annual cost of borrowing money |
Understanding borrowing rates versus saving yields connects directly with smart debt management covered in our good debt vs bad debt explanation.
4. How to Maximize Your Savings APY
To make your cash work harder, adopt these practical savings habits:
-
Look for High-Yield Savings Accounts (HYSAs): Traditional brick-and-mortar banks often offer base savings rates as low as 0.01% APY, whereas online banks frequently offer high-yield accounts with APYs above 4.00% or 5.00%.
-
Check for Rate Guarantees: Savings account APYs are variable, meaning banks can adjust rates up or down based on central bank benchmark policy changes. If you want a fixed rate, consider locking funds in a Certificate of Deposit (CD).
-
Avoid Hidden Fees: Monthly maintenance fees can quickly erode your earned interest. Always choose accounts with zero monthly service fees and no minimum balance penalties.
Building a dedicated high-yield savings buffer outlined in how to build an emergency fund protects your financial independence during unexpected life events. As your savings grow, maintaining strong credit profile habits detailed in our credit score vs credit report difference ensures you qualify for low interest rates on future loans.
Want More Insights to Grow Your Digital Presence & Daily Productivity?
Whether you need to fix your website’s technical performance or build a smarter, burnout-free work routine, NewsUpTo delivers practical guides to keep you ahead.
Leave feedback about this