
If you leave your extra savings sitting in a standard traditional bank account, your money is likely earning fractions of a single percent in interest each year. As inflation increases the cost of living, cash stored in low-interest accounts loses purchasing power over time.
To earn a better return on your idle cash without taking on market risk, financial advisors frequently recommend opening a high yield savings account (HYSA).
Below is a complete, beginner-friendly guide explaining what a high yield savings account is, how it works, and how to use one effectively to grow your cash reserves.
1. How Does a High Yield Savings Account Work?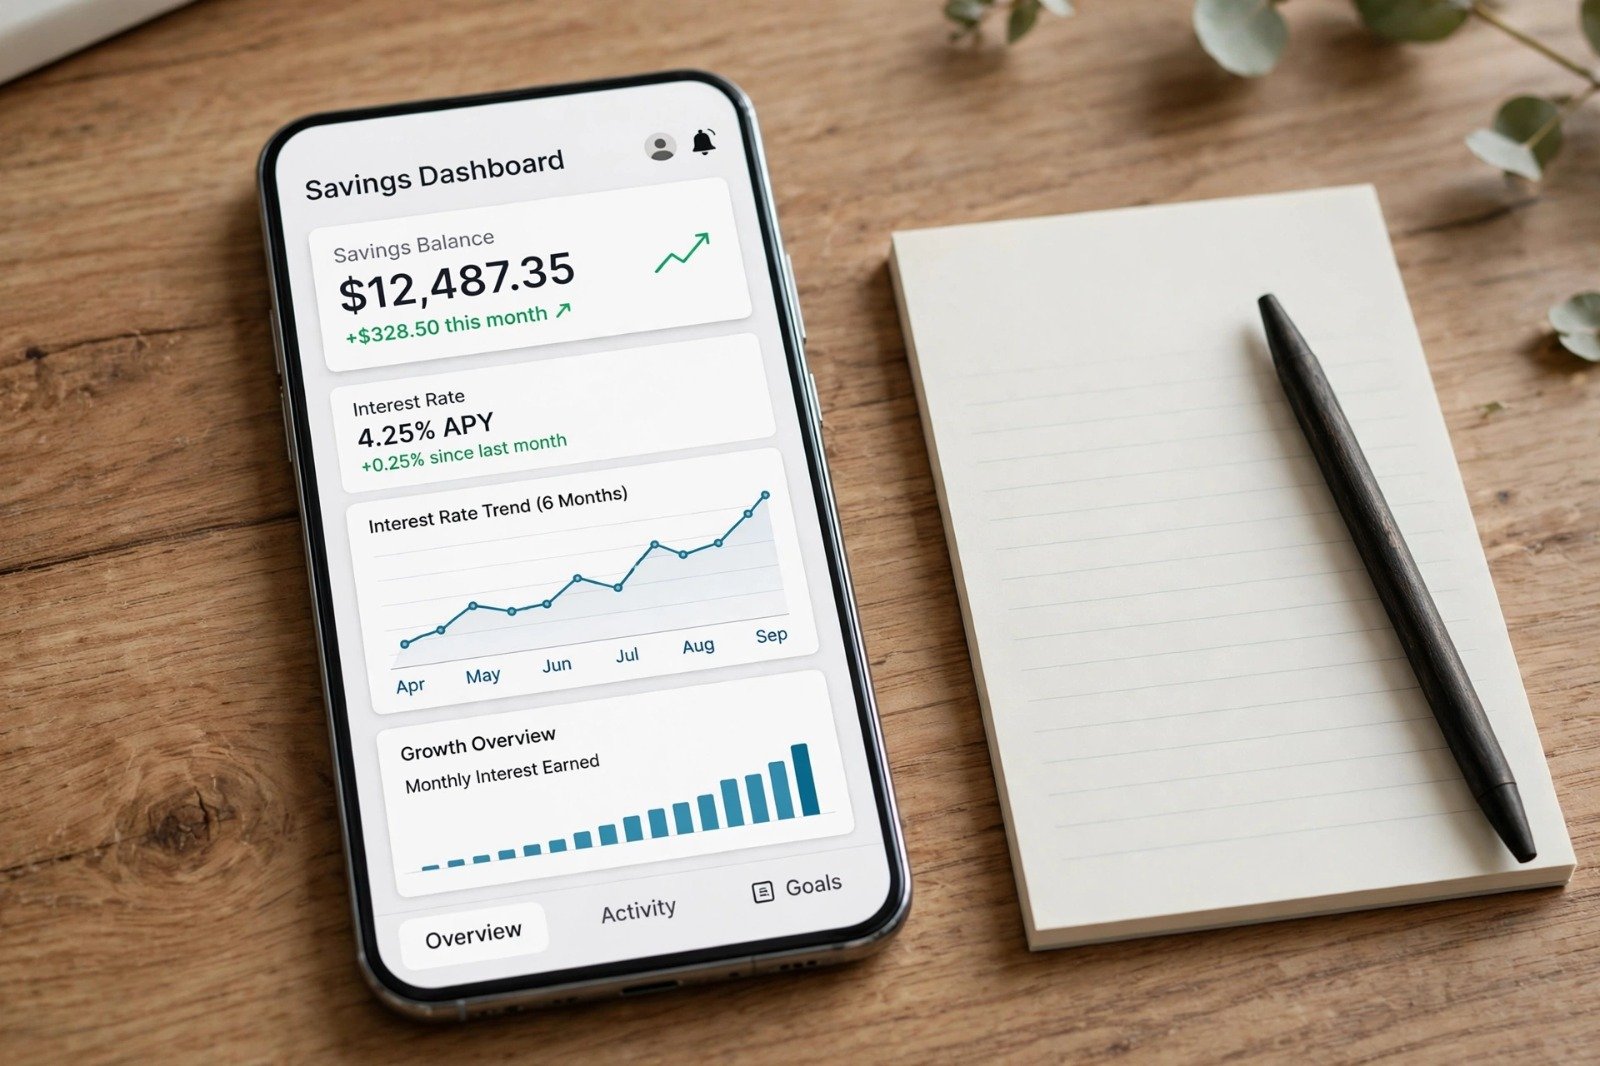
A high yield savings account operates just like any regular savings account you might open at a local bank branch:
-
Earning Interest: The bank pays you interest simply for keeping your money deposited with them.
-
High APY: While traditional banks might offer an Annual Percentage Yield (APY) as low as 0.01%, high yield savings accounts frequently offer rates between 4% and 5% (depending on central bank interest rates).
-
Compounding Power: Most HYSAs compound interest daily or monthly, meaning you earn interest on both your initial deposit and the interest added in previous months.
Online banks are able to offer higher rates because they operate without the massive overhead costs of maintaining physical brick-and-mortar branches.
2. High Yield Savings Account vs Traditional Savings Account
Understanding how an HYSA compares to a standard traditional savings account highlights why switching can make a substantial financial difference.
| Feature | High Yield Savings Account | Traditional Savings Account |
| Typical APY | High (often 4.00% to 5.00%+) | Very Low (often 0.01% to 0.05%) |
| Bank Type | Primarily Online Banks | Traditional Physical Branches |
| Safety & Insurance | Government Insured (e.g., FDIC) | Government Insured (e.g., FDIC) |
| Liquidity | High (easy electronic transfers) | High (ATM cards, in-person withdrawals) |
| Monthly Fees | Usually $0 | Often requires minimum balance to waive |
Storing your liquid cash in an HYSA works exceptionally well when separating planned goals, as discussed in our guide on the sinking fund vs emergency fund difference.
3. Are High Yield Savings Accounts Safe?
Yes, high yield savings accounts carry the exact same safety protections as traditional brick-and-mortar bank accounts, provided you choose an insured institution.
-
Deposit Insurance: In the United States, ensure your chosen bank is insured by the Federal Deposit Insurance Corporation (FDIC). In other regions, ensure it is covered by national deposit protection schemes.
-
Coverage Limit: FDIC protection covers up to $250,000 per depositor, per insured bank, for each account ownership category.
-
Low Risk: Unlike stocks, real estate, or crypto, your principal deposit is guaranteed not to lose value due to market swings.
Maintaining insured cash reserves complements healthy financial management, similar to tracking incoming business funds covered in how to make an invoice for small business, or controlling everyday habits outlined in how to stop impulse buying simple tips.
4. What to Look for When Choosing an HYSA
Before opening an account, compare these essential features across different online banks:
-
Competitive APY: Check if the rate is consistently high or just an introductory promotional rate.
-
Zero Maintenance Fees: Look for accounts with no monthly maintenance fees that eat into your earned interest.
-
No Minimum Balance Requirements: Choose accounts that do not charge penalties if your balance dips below a certain threshold.
-
Fast Transfer Options: Ensure the bank offers quick, easy electronic transfers back to your primary checking account.
Want More Insights to Grow Your Digital Presence & Daily Productivity?
Whether you need to fix your website’s technical performance or build a smarter, burnout-free work routine, NewsUpTo delivers practical guides to keep you ahead.
Leave feedback about this