
Paying off high-interest debt with a predictable, salaried paycheck is straightforward: you calculate your fixed monthly expenses, determine your surplus, and set up automatic debt payments.
However, for freelancers, gig workers, real estate agents, and commission-based earners, monthly income changes constantly. Making large, fixed debt payments during a high-earning month feels easy, but a lean month can leave you struggling to cover minimum payments without relying on credit cards again.
Managing debt on an unpredictable income requires a flexible framework known as targeted budgeting.
Here is your complete guide to smoothing variable cash flow, protecting your business, and eliminating debt rapidly without taking on unmanageable financial stress.
How Do You Pay Off Debt with Variable Income?
To eliminate debt when your earnings fluctuate month to month, structure your finances around four core steps:
-
Calculate Your Baseline Budget: Determine the minimum dollar amount required to cover basic living costs and minimum debt payments.
-
Build an Income Smoothing Buffer: Maintain a dedicated cash cushion (1 to 2 months of baseline expenses) to bridge income dips between client invoices.
-
Set Up a Percentage-Based Debt Allocation: Instead of committing to a rigid dollar amount, allocate a fixed percentage of your high-earning months directly to debt principal.
-
Use a Modified Debt Avalanche or Snowball: Pay minimums on all accounts during lean months, and dump surplus windfalls onto your targeted priority debt during high-earning months.
Step 1: Establish Your Baseline Budget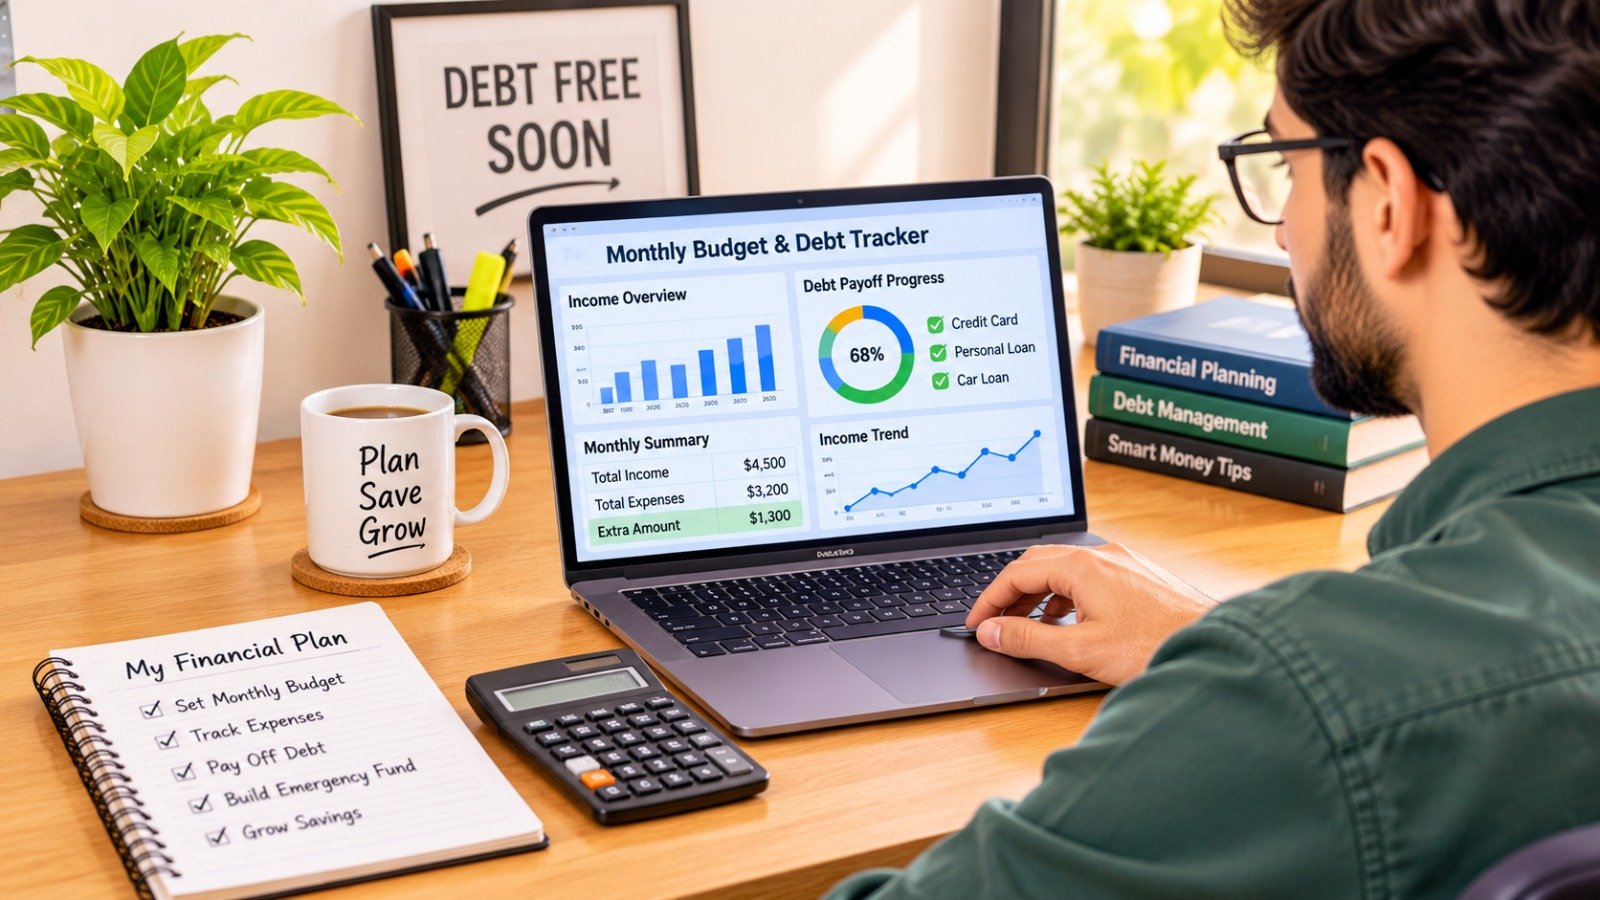
Traditional fixed budgeting fails variable earners because it assumes consistent revenue. Targeted budgeting begins with identifying your absolute lowest operational baseline.
According to financial extension guidance from Penn State Extension, managing an irregular income effectively requires separating non-negotiable living costs from discretionary spending.
Calculate your Baseline Expenses by adding up:
-
Essential housing and utilities (rent, electricity, internet).
-
Baseline groceries and necessary health expenses.
-
Basic business operating costs (software subscriptions, self-employment tax reserves).
-
Minimum monthly payments on all existing debt balances.
Any income earned above this baseline total represents your discretionary surplus, which can be directed toward emergency reserves or accelerated debt payoff.
Step 2: Create an “Income Smoothing” Hill-and-Valley Buffer
One of the biggest mistakes freelancers make is putting all surplus cash from a big invoice straight toward debt payoff, leaving zero cash reserves for the following month. If client payments are delayed, you are forced to use credit cards for daily living costs, canceling out your debt progress.
Before making aggressive debt payments, build a Hill-and-Valley Buffer (also called an Income Buffer).
How the Buffer Works
-
Deposit all incoming client payments into a separate “Buffer” bank account.
-
Pay yourself a fixed monthly “salary” from the Buffer account into your personal checking account based on your baseline budget.
-
During high-income months (“hills”), allow extra funds to accumulate in the Buffer.
-
During low-income months (“valleys”), draw from the Buffer to maintain consistent minimum debt payments without missing due dates.
Learn how to structure your personal safety net by exploring our guide on how to build an emergency fund.
Step 3: Choose a Flexible Repayment Framework
Once your baseline budget and income buffer are active, pick a debt payoff structure that accommodates fluctuating income.
| Feature / Metric | Traditional Fixed Strategy | Variable Percentage Strategy |
| Payment Model | Fixed dollar amount every month (e.g., $500/mo). | Minimums + variable % of monthly surplus. |
| Lean Month Safety | Low (Risk of budget deficit). | High (Scales down automatically during slow months). |
| High Month Potential | Moderate (Standard fixed payment applied). | High (Large client wins yield massive principal drops). |
| Stress Level | High during income drops. | Low (Calculated based on actual cash on hand). |
The Percentage Surplus Strategy
Rather than promising to pay an extra fixed dollar amount (such as $600 every month), commit to a percentage rule. For example:
-
50% of monthly surplus goes directly to your target debt principal.
-
30% of monthly surplus remains in your Income Buffer account.
-
20% of monthly surplus goes toward quarterly self-employment taxes or business savings.
This ensures that when you land a major contract, a substantial portion pays down debt without draining your operational cash reserves.
Step 4: Pick the Right Repayment Order
When prioritizing which debts to attack first, the two standard models detailed by the Consumer Financial Protection Bureau apply: the Debt Avalanche and the Debt Snowball.
The Debt Avalanche (Mathematically Optimal)
Direct all extra percentage surplus to the debt carrying the highest Annual Percentage Rate (APR), while paying minimums on everything else. This minimizes total interest paid over time, making it ideal for variable earners carrying high-interest credit card debt.
The Debt Snowball (Psychologically Optimal)
Direct all extra percentage surplus to the account with the smallest overall balance. Eliminating a small $400 account quickly removes a required monthly minimum payment entirely, lowering your baseline budget requirement for future months.
Organize your overall personal cash flow effectively with our beginner guide to budgeting.
Step 5: Automate Minimums and Batch Extra Payments
To protect your credit score, separate minimum payments from extra principal payments:
-
Automate Minimums: Set up automatic monthly payments for the minimum amount due on all debt accounts using your baseline budget funds. This guarantees zero missed payment penalties or credit score drops.
-
Batch Manual Extra Payments: On the final day of each month, calculate your total net surplus. Execute a manual, one-time extra payment directed straight to the principal of your target debt.
If you are looking to increase your monthly income surplus, review our list of high paying side hustles.
To understand how credit tracking agencies monitor your payment consistency during debt reduction, review Experian’s Guide to Debt Management.
Want More Insights to Grow Your Digital Presence & Daily Productivity?
Whether you need to fix your website’s technical performance or build a smarter, burnout-free work routine, NewsUp To delivers practical guides to keep you ahead.
Leave feedback about this